Bike Loan Finance Online Personal Loan Repayment Calculator
Calculate repayments with our Personal Loan Calculator. Compare loan terms, view repayment schedules, and plan your personal finance with confidence.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Personal Loan Details:
Important!
Personal Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Personal Loan Amortisation Calculator
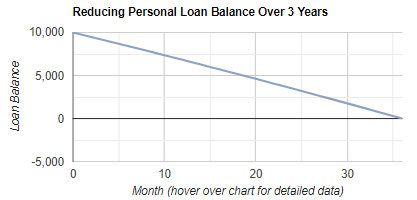
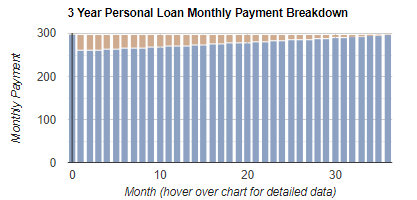
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Personal Loan Repayment Calculator
Our Personal Loan Repayment Calculator helps you estimate your ongoing loan repayments and the total cost of borrowing before you apply. By adjusting the loan amount, loan term and interest rate, you can compare scenarios and choose a repayment level that better fits your budget. It also provides an amortisation view so you can see how each repayment is split between interest and principal over time.
Important note for ASIC compliance: this calculator provides general information only and does not take into account your objectives, financial situation or needs. Results are estimates and may not include lender fees, comparison rates, commissions, insurance, redraw features, or changes to your interest rate. Always check a lender’s final quote and loan contract before deciding.
How to complete the form for the best result
1. Loan Amount Required: Enter the total amount you want to borrow in Australian dollars as a whole number (no decimals or commas). Use the amount you actually need, not the maximum you might be approved for, to avoid overpaying interest.
2. Term of Loan: Select the number of years you plan to repay the loan over. A longer term can reduce the monthly repayment, but typically increases the total interest paid over the life of the loan.
3. Interest Rate: Choose an annual interest rate for the simulation. If you have a lender quote, use that rate. If not, test a conservative range to understand best case and worst case outcomes.
4. Calculate: Click the calculate button to generate your results.
How to interpret the results
1. Repayment estimate: Treat the repayment figure as your baseline commitment. Stress-test your budget by increasing the rate or shortening the term to see if repayments remain affordable.
2. Amortisation and graphs: Review the month-by-month amortisation view and charts to understand how the balance reduces and how early repayments often include a higher interest portion, shifting toward more principal over time.
3. Compare scenarios: Re-run the calculator with different terms and rates to balance affordability (cash flow) against total interest (overall cost).
Buying new or used, from a dealer or a private seller, can affect motorcycle finance documentation, checks, settlement and lender assessment. Here's what Australian buyers should consider before applying. - read more
Owning a motorbike is more than just transportation; it's a lifestyle choice that brings with it a unique sense of freedom and exhilaration. Whether you're weaving through city traffic or enjoying a weekend getaway down the Great Ocean Road, the experiences ahead are limitless. - read more
Motorcycle loan repayments are shaped by the amount borrowed, interest rate, loan term, fees, repayment frequency and any balloon or residual payment. Understanding how these factors work together can help Australian riders compare finance options and estimate affordability before applying. - read more
Buying a bike can be an exciting journey, but navigating the financial aspect can sometimes feel overwhelming. This is where prequalifying for a bike loan can make all the difference. But what exactly does prequalifying mean? - read more
Fresh RBA credit data has given motorcycle buyers another reason to keep their finance planning practical. The latest lending indicators point to a household borrowing market that remains active, even as consumers continue to face elevated living costs and lenders maintain close checks on affordability. For riders, that means competition for finance has not disappeared, but neither has the need to prove that a loan is manageable. - read more
Financial markets have entered September with a more cautious view of how quickly borrowing costs may fall. Recent market coverage suggests investors are less willing to assume a smooth run of Reserve Bank rate cuts, with inflation progress still uneven and consumer activity proving more resilient than many borrowers might have expected. - read more
Fresh September personal loan comparison data has reinforced a familiar but important message for Australians planning a motorcycle purchase: the rate shown at the top of an offer is only the starting point. For riders weighing up a new commuter bike, a used adventure machine or a weekend cruiser, the spread between competitive loan offers and higher-cost credit can still make a meaningful difference to the total amount paid over the life of the loan. - read more
Fresh August personal loan comparison data has again highlighted a key lesson for Australian motorcycle buyers: the cheapest-looking rate is not always the lowest-cost loan once fees, loan structure and eligibility criteria are considered. For riders planning a new commuter bike, a used weekend machine or an upgrade before spring, the latest market snapshot reinforces the value of slowing down before signing. - read more